The Autumn Budget lands on 28 October 2026. If you’re a property investor or have been thinking about becoming one, the weeks leading up to it are generating the kind of noise that makes it easy to either panic into a decision or freeze and do nothing.
Neither of those is the right response. Here’s what’s confirmed, what’s still speculation, and how to think about the next twelve weeks.
What’s Already Confirmed
Rental income tax is going up from April 2027
If you own investment property in your personal name, your tax rate on rental profit is increasing. Basic rate taxpayers move from 20% to 22%. Higher rate from 40% to 42%. Additional rate from 45% to 47%.
This is confirmed legislation. It applies only to landlords owning personally. If you own through a limited company, corporation tax stays at 19% on profits up to £50,000. For higher and additional rate taxpayers, the gap between personal and corporate tax treatment has never been wider. More than half of all new buy-to-let purchases in the UK are now going through limited companies, and April 2027 is accelerating that shift further.
If you’re still buying in your personal name and your rental profits are taxed at 40% or above, speak to a tax accountant before your next purchase, not after.
Stamp duty isn’t changing
The Chancellor has explicitly ruled out changes to stamp duty in this Budget. The 5% surcharge on additional residential properties stays. Ignore the rumours.
The mansion tax surcharge
A surcharge of £2,500 to £7,500 per year will apply to properties worth over £2 million from April 2028. It affects a small proportion of buy-to-let investors but worth knowing if you’re looking at higher-value assets.
What’s Still Speculation
Capital gains tax
The most significant speculation heading into October is around CGT. Andy Burnham has expressed interest in aligning CGT rates more closely with income tax. Currently CGT on residential property sits at 18% for basic rate taxpayers and 24% for higher rate. Nothing is confirmed and independent analysis suggests full alignment would cost over £7 billion annually, making wholesale change in a single Budget unlikely.
But the speculation itself is already driving behaviour. Landlords considering selling are accelerating completions before 28 October just in case rates rise. That creates a temporary window of motivated sellers and stronger negotiating positions that disappears once Budget day passes.
The Fairer Share property value charge
Andy Burnham has backed replacing council tax with an annual property value charge but has explicitly ruled it out for this Budget. Don’t let it influence any decision you make in the next twelve weeks.
Rates, Inflation, and the Cost of Waiting
The Bank of England held its base rate at 3.75% at its July meeting, with three members voting to raise it to 4.00%. The next decision is 17 September, six weeks before the Budget.
Your mortgage rate and the base rate aren’t the same thing. Lenders price products based on their own funding costs and forward expectations, not just where rates sit today. With three MPC members already voting for a rise, lenders are watching closely. Fixing a mortgage before the September decision means buying certainty in an uncertain market, and that certainty has real value.
The other cost that rarely gets discussed is uninvested capital. With inflation at 2.6% and expected to rise, cash in a savings account is quietly losing purchasing power every month. Quality property in high-demand rental markets has historically been one of the more reliable long-term inflation hedges available to private investors.
Mortgage and base rate figures correct as at August 2026. Rates change frequently — speak to a qualified mortgage broker for current product availability.
Why the North West Outlasts Budget Speculation
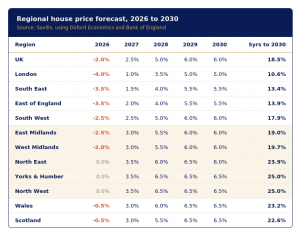
London house prices are forecast to fall 2% in 2026 and grow just 10.6% to 2030. The North West tells a different story. Savills forecast 25% growth in the North West and Yorkshire to 2030, more than double the London figure, driven by stronger affordability, growing populations, and infrastructure investment that has been reshaping the regional economy for a decade.
A quality buy-to-let in Manchester or Salford at £200,000 currently yields 5.5% to 6%, significantly ahead of the 3.5% to 4.5% you’d expect from comparable London stock at double the price. Lower entry point, stronger yield, better five-year growth forecast.
Westminster policy changes rarely undermine strong regional fundamentals. Demand for quality rental housing in the North West is driven by population growth, graduate retention, and the northward movement of jobs and investment that has been building for years.
Should You Act Before October or Wait?
The honest answer depends on your ownership structure, your location strategy, and the quality of the deal in front of you.
Acting before October makes most sense if you’re buying through a limited company, which insulates you from the April 2027 personal name tax changes, or if you’ve identified a motivated seller who wants to complete before Budget day.
Before acting, answer two questions. Have you spoken to a tax accountant about your ownership structure? The April 2027 changes make this more consequential than it’s ever been. And does the deal stack up on today’s numbers, not on optimistic assumptions about future rate cuts?
The Bottom Line
Smart investors don’t try to time the government. They structure deals that work regardless of who’s in the Treasury.
What won’t change on 28 October is the long-term case for quality, well-located buy-to-let property in the North of England. The Savills data, the population growth, the yield advantage over London — none of that depends on what the Chancellor announces.
What is time-sensitive is the seller psychology the Budget speculation is currently creating. That window closes on Budget day.
If you want to understand how the current environment applies to your situation, book a free discovery call with James. No pitch, no pressure. Just an honest conversation about whether property makes sense for you right now.
Book a free discovery call – https://fraterpropertypartners.com/work-with-us/
This article is for informational purposes only and does not constitute financial or tax advice. Property investment involves risk. Always seek independent professional advice before making investment decisions. Capital at risk.